COVID-19 SITUATION
The emergency of Covid-19 at the beginning of 2020 took the world by surprise (delivering a shock), just as the global economy had begun to stabilize from trade wars in the preceding years.
The emergency of Covid-19 at the beginning of 2020 took the world by surprise (delivering a shock), just as the global economy had begun to stabilize from trade wars in the preceding years.
Most European countries are past or at the peak of COVID-19 infection and their governments are now looking towards strategies to reactivate their economies.
By 2030 there will be an additional 1.2 billion people in the world with significant regional and country disparities. Equally significant is the general population is living and working longer.
The global economy is now gradually reopening. The leading indicators are positive and suggest that a V-shaped recovery is still on the table.
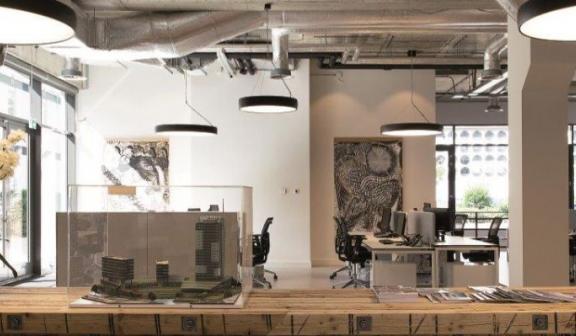
The outbreak of the pandemic has imposed a mass telecommuting experiment by companies on their employees everywhere around the world. Over the short term, office markets are on hold and prompting rethinking about how the future office will work.
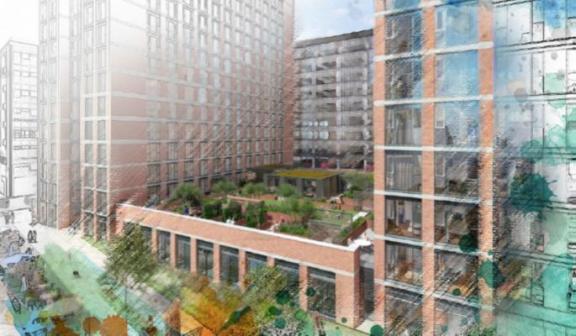
THE BUILD-TO-RENT SECTOR is an extension of the PRS sector as European housing markets have become institutionalised amid a lack of housing supply.
2022 is shaping up to be a transformative year for real estate markets in Europe. It has been a tough few months in macroeconomic terms, with a slowing economy, high inflation and an elevated cost of debt.
There is resemblance of calm after the storm for the European economy and real estate markets. Following significant repricing in 2022, we expect a smaller scale adjustment in yields this year.
Investment regained momentum over 2021 after the Covid-19 crisis to reach pre-crisis levels as economies reopened with control of the pandemic outbreak.
The rapid acceleration in financing costs from mid-2022 destabilized pricing in the market, resulting in investment plummeting by Q4 as buyers and sellers pulled back.